The Best No-Annual-Fee Credit Card Trio in Canada (2026 Strategy)
⚡ Quick Takeaways: The $0 Fee Canadian Dream Team
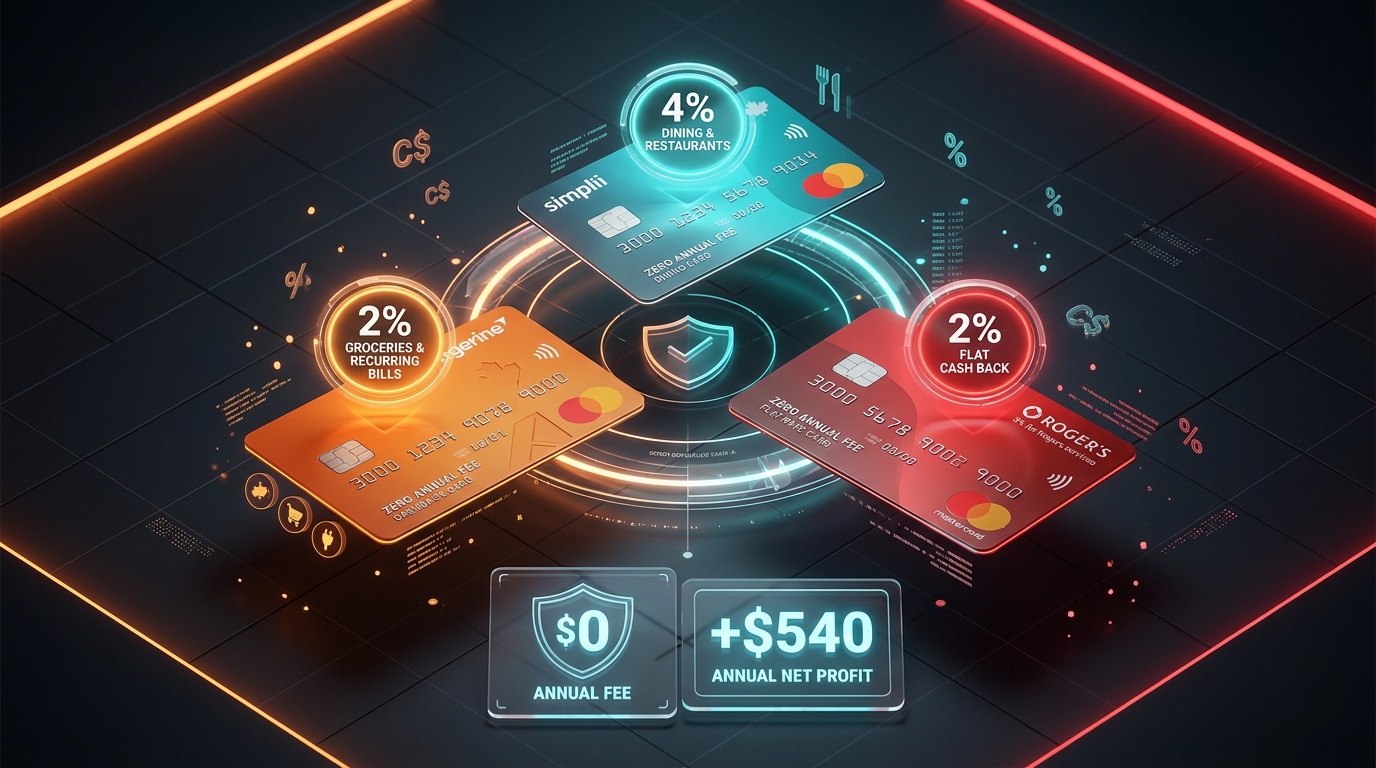
- The Optimal 3-Card Trio: By combining the Tangerine Money-Back Mastercard (2% on 3 chosen categories), Simplii Financial Cash Back Visa (4% on dining & takeout), and the Rogers Mastercard (2% flat base rate, or 3% on Rogers/Fido/Shaw redemption), you cover virtually 100% of Canadian retail spend.
- Mathematical Proof: On a typical Canadian household annual spend of $26,400 ($2,200/month), this zero-fee trio generates $624 to $732 in net annual cash back, beating single $120-$150 premium rewards cards by $100 to $200 per year.
- Zero Acceptance Anxiety: Combining two Mastercards and one Visa guarantees full acceptance across discount grocers (No Frills, Food Basics), wholesale clubs (Costco), and independent Asian restaurants that decline American Express.
- Uncapped Category Strength: Tangerine features zero spending caps on its 2% categories, while Simplii provides a generous $5,000 annual ceiling on 4% restaurant meals and food delivery apps.
In the world of credit card rewards, marketing departments at Canada's Big Five banks spend millions convincing consumers that paying a $120, $139, or $150 annual fee is mandatory to unlock meaningful rewards. While premium travel and cash back cards certainly have their place for frequent flyers and heavy spenders, the cold mathematical reality is that most moderate Canadian spenders are overpaying for cards they underutilize.
When you carry a single $120 annual fee card, its lucrative 4% earn rate usually only applies to one or two categories (such as groceries and gas). All your remaining expenses—online shopping, dining, home improvement, drugstores, and Costco runs—tumble to a dismal 1% base rate, while the $120 fee immediately erodes your net cash back. By constructing a coordinated 3-card zero-annual-fee portfolio, you can capture accelerated multipliers across every spending pillar and keep 100% of your earnings.
The Trifecta: Roles, Multipliers & Allocation
1. Tangerine Money-Back Mastercard ($0 Fee)
Primary Role: Category Specialist for Household & Fixed Recurring Costs | Key Rate: 2.0% cash back in up to 3 chosen categories (0.5% base) | Spending Cap: None (Unlimited 2% spend)
The Tangerine Money-Back Mastercard allows cardholders to select two 2% categories from a list of ten options—and unlocks a third 2% category simply by directing monthly cash back into a free Tangerine Savings account. Unlike almost every other cash back card in Canada, Tangerine imposes zero spending limits on its 2% tiers, and cash back is deposited automatically every month rather than held hostage until December.
Optimal Category Selection for the Trio:
- Recurring Bill Payments: Utilities, insurance, gym memberships, and streaming subscriptions (all billings through automated pre-authorized debit).
- Groceries: Covers your weekly supermarket visits at Metro, Sobeys, Safeway, and discount grocers like No Frills and Food Basics where Amex is declined.
- Home Improvement or Furniture: Captures high-ticket hardware runs at Home Depot, RONA, Lowe's, and IKEA that standard cards code as 1%.
2. Simplii Financial Cash Back Visa Card ($0 Fee)
Primary Role: Food, Bars, Cafes & Food Delivery | Key Rate: 4.0% cash back on restaurant meals, coffee shops, and food apps | Spending Cap: $5,000 per calendar year ($200 cash back ceiling)
Simplii's credit card provides the highest no-annual-fee dining return in Canada. Earning a massive 4.0% cash back on all dining spend, it matches or exceeds cards charging $120+ fees. It covers table service restaurants, neighbourhood coffee shops, pubs, fast food outlets, and third-party delivery apps like Uber Eats, DoorDash, and SkipTheDishes.
Because it operates on the Visa network, you avoid the merchant friction of American Express rejection at mom-and-pop bakeries, sushi joints, and independent bistros. For details on app coding, consult our guide to the best credit cards for dining and takeout in Canada.
3. Rogers Mastercard ($0 Fee)
Primary Role: The Universal Non-Category Catch-All & Warehouse Card | Key Rate: 2.0% flat cash back on all eligible Canadian spend (boosted to 3.0% on telecom redemption) | Spending Cap: None
The Rogers Mastercard (or Rogers Red World Elite Mastercard for households meeting the $80k personal / $150k household income threshold) is the linchpin of this entire strategy. For anyone with at least one eligible qualifying service with Rogers, Fido, or Shaw (such as home internet or a mobile phone plan), the card earns an unlimited 2.0% flat cash back on every single transaction.
Even better, when you redeem accumulated cash back toward your monthly Rogers, Fido, or Shaw bill, Rogers grants a 1.5x redemption bonus, elevating your effective cash back return to an astonishing 3.0% net yield. Because it is a Mastercard, it serves as your dedicated payment method at Costco warehouses and Costco Gas, turning routine warehouse shopping into 2%–3% pure profit.
The Mathematical Proof: Zero-Fee Trio vs Single $120 Premium Card
Let's simulate a typical Canadian single professional or couple with a realistic $2,200 monthly budget ($26,400 annually). We will compare routing this spending through the Zero-Fee Trio against routing it through a conventional Big Five $120 annual fee 4% grocery/gas card (such as the Scotiabank Momentum Visa Infinite or CIBC Dividend Visa Infinite):
| Expense Category | Monthly / Annual Spend | Designated Trio Card | Trio Earn Rate | Trio Annual Cash Back | Single $120 Card Rate | Single Card Return |
|---|---|---|---|---|---|---|
| Dining & Takeout | $400 / $4,800 | Simplii Visa | 4.0% | $192.00 | 2.0% / 1.0% | $96.00 |
| Groceries | $600 / $7,200 | Tangerine Mastercard | 2.0% | $144.00 | 4.0% | $288.00 |
| Recurring Bills & Subscriptions | $300 / $3,600 | Tangerine Mastercard | 2.0% | $72.00 | 2.0% / 4.0% | $72.00 |
| Costco & Gas | $350 / $4,200 | Rogers Mastercard | 2.0% – 3.0% | $84.00 – $126.00 | 1.0% (Costco) | $42.00 |
| Retail, Transit, Home & Misc | $550 / $6,600 | Rogers Mastercard | 2.0% – 3.0% | $132.00 – $198.00 | 1.0% Base | $66.00 |
| Gross Annual Rewards | $2,200 / $26,400 | — | — | $624.00 – $732.00 | — | $564.00 |
| Annual Fees Paid | — | — | — | $0.00 | — | -$120.00 |
| Net Annual In-Pocket Profit | $26,400 Total | — | — | +$624.00 to +$732.00 | — | +$444.00 |
The mathematical outcome is undeniable: despite paying zero dollars in card fees, the Zero-Fee Trio outperforms the single premium card by +$180 to +$288 in net cash back every year. The reason is the base floor: earning 2% to 3% on miscellaneous retail, Amazon, clothing, hardware, and warehouse shopping generates far more compound yield than earning 4% on groceries while sacrificing everything else to a 1% penalty.
What If You Are Not a Rogers or Fido Customer?
If you do not subscribe to home internet, wireless, or television services through Rogers, Fido, or Shaw, the Rogers Mastercard drops to a standard 1.0% flat rate. You can easily adapt the trio by swapping in one of two stellar zero-fee alternatives:
- Alternative A: The Wealthsimple Cash Card: A prepaid Mastercard with $0 annual fee that earns a flat 1.0% cash back on all spend, charges 0% foreign transaction fees abroad (saving you 2.5% on international trips), and pays 3.5% to 4.5% interest on your unspent funds. Read our Wealthsimple Cash Card review.
- Alternative B: American Express SimplyCash Card: Carries a $0 annual fee and awards a flat 1.25% cash back on all purchases with no spending cap, plus 2.0% on groceries up to $15,000/yr. You can use Amex for major retail purchases and keep Tangerine/Simplii for non-Amex merchants.
Network Coverage & Acceptance Strategy
One of the most powerful hidden advantages of this trio is merchant interchange resilience:
- Costco Warehouses & Gas: Costco Canada only accepts Mastercard. Swiping your Rogers Mastercard (or Tangerine Mastercard) nets 2% to 3% right at the checkout lane.
- Discount Supermarkets: Loblaws, No Frills, and Real Canadian Superstore do not accept American Express. Your Tangerine Money-Back Mastercard earns 2% with zero acceptance problems.
- Small Eateries & Bakeries: Many independent Asian restaurants, shawarma shops, and cafes decline Amex due to higher merchant fees. Your Simplii Financial Visa guarantees full acceptance and captures 4% cash back.
How WalletFit Automates the Zero-Fee Trio
Carrying three cards sounds simple, but remembering which card earns 2% on bills, 4% at delivery apps, and 2% at retail can lead to card-tap confusion. WalletFit turns this setup into an effortless autopilot engine:
- Terminal MCC Lookup: WalletFit's real-time merchant classification engine tells you exactly which card produces the highest net yield before you tap your phone.
- Cap & Category Routing: Monitors your $5,000 annual Simplii dining limit and automatically reroutes dining to your Rogers card once capped.
- Portfolio Simulation: Evaluates your custom spending against 50+ Canadian cards using our three-card portfolio optimization methodology.
Frequently Asked Questions
Can a no-annual-fee credit card portfolio really beat a $120-$150 premium rewards card?
Yes, especially for moderate spenders spending between $1,500 and $3,000 monthly. While a premium card earns 4% on groceries or gas, its non-category base earn rate is typically only 1%, and the $120 to $150 annual fee cuts directly into net rewards. A zero-fee trio (Simplii 4% dining, Tangerine 2% chosen categories, and Rogers 2% flat base) generates $600+ in gross rewards with $0 deducted in annual fees, netting $100 to $200 more annually than a single fee-bearing card.
What are the three best no-annual-fee credit cards to pair together in Canada?
The definitive zero-fee Canadian trio consists of: 1) Tangerine Money-Back Mastercard (2% on 3 customizable categories like recurring bills, groceries, or furniture with no caps), 2) Simplii Financial Cash Back Visa (4% on restaurants, bars, and food delivery apps up to $5,000/yr), and 3) Rogers Mastercard (2% flat cash back on all non-category spend, or 3% when redeemed against Rogers/Fido/Shaw telecom services).
What if I am not a Rogers, Fido, or Shaw customer?
If you don't have eligible Rogers services, you earn 1% base cash back on the Rogers card. Non-Rogers customers can replace the Rogers card with the Wealthsimple Cash Card (Mastercard, 1% cash back + 0% foreign transaction fees + interest on balance) paired with the American Express SimplyCash Card ($0 annual fee, 1.25% flat cash back everywhere Amex is accepted) to maintain a superior non-category earn floor.
Does holding three credit cards hurt my Canadian credit score?
Over time, holding three credit cards actually strengthens your Canadian credit score (Equifax and TransUnion). Having three open tradelines expands your total available credit limit, which naturally drives down your credit utilization ratio (ideally kept below 30%). As long as you make all monthly payments on time and in full, a 3-card setup establishes a resilient, mature credit profile.
Build Your Zero-Fee Dream Wallet
WalletFit identifies merchant category codes, tracks category spending caps, and calculates exact net returns across 50+ Canadian cards so you never pay unnecessary annual fees.
Related Canadian Credit Card & Portfolio Guides
- The 4-card Canadian dream wallet (2026): Upgrading from zero-fee to the ultimate points & cash engine.
- Tangerine vs Simplii Cash Back showdown: No-fee digital banking cards compared.
- Rogers Red World Elite Mastercard review: 2% flat cash back & 3% bill redemption math.
- Three-card portfolio optimization guide: Constructing the ultimate Canadian wallet.
- Best credit cards for dining and takeout: 2026 Tier List for restaurants and food delivery.
- Best credit cards for gas & EV charging: Fuel rewards and charger MCC rules.
- Wealthsimple Cash Card review: 0% FX fees and high-interest cash back.
- Top Canadian credit cards overall: Canada's 10 best credit cards ranked.