Tangerine Money-Back vs Simplii Cash Back Visa: Battle of the No-Fee Contenders
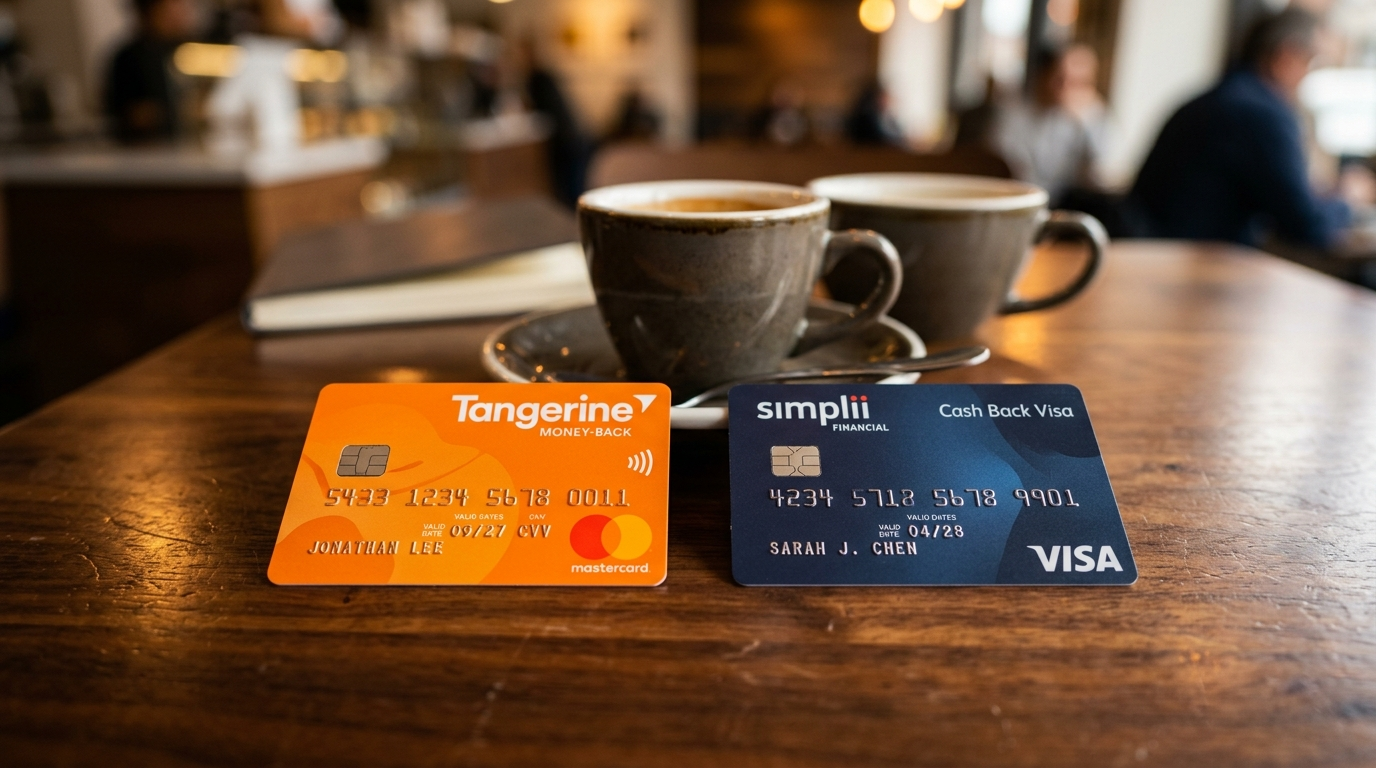
Executive Summary: Which No-Fee Cash Back Card Wins?
- Simplii Wins for Dining & Bars: Simplii Financial Cash Back Visa delivers an unbeatable 4% cash back on restaurant, bar, and coffee purchases (up to $5,000 annual spend), making it Canada's top zero-fee dining card.
- Tangerine Wins for Flexibility & Uncapped Spend: The Tangerine Money-Back Mastercard lets cardholders pick up to 3 categories at 2% cash back with zero spending caps (from 10 diverse categories like Groceries, Recurring Bills, and Home Improvement).
- Payout Velocity: Tangerine pays cash back monthly (earning interest immediately in a high-interest savings account), whereas Simplii holds all cash back until the December billing statement.
- Network Advantage: Tangerine operates on Mastercard (accepted at Loblaws, No Frills, and Costco), while Simplii operates on Visa (declined inside Costco warehouses).
- The Optimal Duo Strategy: Carrying both cards yields 4% on dining plus 2% on groceries, bills, and gas with $0 in total annual fees.
For budget-conscious Canadian consumers, students, young professionals, and debt-averse spenders, paying a $120 to $150 annual fee for a premium rewards card is often a non-starter. Fortunately, Canada's leading digital banks—Scotiabank-owned Tangerine and CIBC-owned Simplii Financial—have engineered two of the most lucrative no-annual-fee cash back credit cards in North America.
Both products provide cash yields that rival fee-charging cards in targeted merchant categories. However, their underlying reward engines could not be more distinct: Simplii concentrates fire on restaurant spending with an aggressive 4% headline rate, while Tangerine grants cardholders surgical control through customizable, uncapped 2% bonus categories. In this head-to-head comparison, we analyze the earning rates, spending caps, payout mechanisms, and demonstrate how pairing both cards inside WalletFit yields maximum return with zero annual costs.
Core Specifications: Tangerine vs Simplii at a Glance
Before examining category math and monthly simulations, here is how both cards compare across foundational metrics:
| Feature / Parameter | Tangerine Money-Back Mastercard | Simplii Financial Cash Back Visa | Strategic Winner |
|---|---|---|---|
| Annual Fee | $0 CAD | $0 CAD | Tie ($0 for life) |
| Payment Network | Mastercard (Universal) | Visa | Tangerine (Works at Loblaws & Costco) |
| Top Category Multiplier | 2.0% Cash Back | 4.0% Cash Back | Simplii (Double the rate on dining) |
| Top Category Scope | Up to 3 selectable categories | Restaurants, bars, coffee shops | Tangerine (Customizable) |
| Category Spending Cap | No Cap (Unlimited 2%) | $5,000 / year ($200 max bonus) | Tangerine (Zero caps) |
| Secondary Multipliers | N/A (All 3 categories earn 2%) | 1.5% on gas, groceries, pharmacy, pre-authorized | Tangerine (2.0% > 1.5%) |
| Secondary Category Cap | Unlimited | $15,000 / year cumulative | Tangerine |
| Base Earning Rate | 0.5% Cash Back | 0.5% Cash Back | Tie |
| Cash Back Payout Frequency | Monthly | Annual (December Statement) | Tangerine (Instant compounding) |
| Minimum Personal Income | $12,000 CAD | $15,000 CAD | Tangerine (Slightly easier access) |
Tangerine Money-Back Mastercard: The Art of Category Customization
The definitive strength of the Tangerine Money-Back Mastercard is flexibility. Instead of forcing you into predetermined spending buckets that might not match your lifestyle, Tangerine lets you select 2 categories at 2% cash back by default—and unlocks a 3rd category at 2% cash back when you have your cash back deposited into a free Tangerine Savings Account.
The 10 Selectable Tangerine 2% Spending Categories
Cardholders can reallocate their 2% categories at any time through the Tangerine mobile app or online banking (changes take effect on the first day of the next billing cycle):
- Groceries (MCC 5411): Supermarkets including No Frills, Metro, Sobeys, Loblaws, and Superstore.
- Restaurants (MCC 5812, 5814): Dine-in restaurants, fast food, cafes, and food delivery apps.
- Gas & EV Charging (MCC 5541, 5542): Gas stations and electric vehicle charging points.
- Recurring Bill Payments: Automatic pre-authorized bills (telecom, utilities, insurance, subscriptions).
- Drugstore / Pharmacies (MCC 5912): Shoppers Drug Mart, Rexall, and local pharmacies.
- Home Improvement (MCC 5200, 5211): Home Depot, Lowe's, RONA, Canadian Tire, and hardware retailers.
- Entertainment (MCC 7832, 7922): Movie theatres, live concerts, and ticket agencies.
- Public Transportation & Parking: Transit passes, trains, taxis, Uber/Lyft, parking meters.
- Hotel / Motel (MCC 7011): Direct hotel reservations and lodging accommodations.
- Furniture (MCC 5712): IKEA, Structube, and major furniture and home furnishing stores.
The Hidden Advantage: No Spending Ceilings
Unlike almost every other Canadian cash back card on the market, Tangerine's 2% categories feature zero spending caps. Whether you spend $300 a month on groceries or drop $6,000 on home renovations at Home Depot in a single afternoon, you earn the full 2% cash back on every single dollar.
Simplii Financial Cash Back Visa: The 4% Dining Powerhouse
Where Tangerine offers broad versatility, the Simplii Financial Cash Back Visa Card delivers concentrated firepower. Its standout proposition is straightforward: earn 4% cash back on eligible dining and drinking establishments with zero annual fee.
- 4.0% Cash Back on Dining: Applies to restaurants, bars, pubs, cafes, coffee shops, and food delivery platforms (Uber Eats, DoorDash, SkipTheDishes) up to an annual net spend of $5,000 per calendar year (yielding up to $200 in bonus cash). Once the $5,000 cap is reached, dining purchases earn 0.5%.
- 1.5% Cash Back on Everyday Essentials: Earn 1.5% on eligible gas, grocery, drugstore purchases, and pre-authorized recurring payments up to a combined spending cap of $15,000 per calendar year ($225 max return, then 0.5%).
- 0.5% Base Catch-All: Unlimited 0.5% return on all other retail spending.
Understanding the Simplii Annual Cap Cliff
The major operational catch with Simplii is its $5,000 dining cap. That works out to roughly $416 per month. If you eat out frequently or regularly order weekend takeout with friends, you will hit this ceiling well before the end of the calendar year. Once crossed, your earn rate drops instantly from 4.0% down to 0.5%—an 87.5% drop in rewards velocity. That is where tracking tools like WalletFit become critical.
Payout Mechanics: Monthly Compounding vs Annual December Payout
One of the most stark practical differences between Tangerine and Simplii is when you actually receive your money:
Cash Back Liquidity & Time Value of Money
- Tangerine (Monthly Liquidity): Cash back is calculated and paid out on every single monthly billing cycle. When deposited into a Tangerine High-Interest Savings Account (HISA), your rewards earn compounding interest immediately throughout the entire year.
- Simplii (Annual Illiquidity): All accumulated cash back is held by Simplii throughout the calendar year and disbursed as a single lump-sum statement credit on your December billing statement. If you close your card before December, you risk forfeiting accumulated unbilled cash back.
Mathematical Spending Simulation: $1,200 Monthly Budget
To evaluate which card generates greater net cash return, let us model an average Canadian young professional or couple spending $1,200 monthly ($14,400 per year) across core household categories:
| Expense Category | Monthly Spend | Annual Spend | Tangerine Solo (Groceries, Bills, Gas) | Simplii Solo (Dining Focus) | The Tangerine + Simplii Combo |
|---|---|---|---|---|---|
| Dining, Bars & Coffee | $350 | $4,200 | $21.00 (0.5% Base) | $168.00 (4.0% Simplii) | $168.00 (Simplii 4%) |
| Groceries (Loblaws / Metro) | $450 | $5,400 | $108.00 (2.0% Tangerine) | $81.00 (1.5% Simplii) | $108.00 (Tangerine 2%) |
| Recurring Utilities & Phone | $200 | $2,400 | $48.00 (2.0% Tangerine) | $36.00 (1.5% Simplii) | $48.00 (Tangerine 2%) |
| Gas & Daily Transit | $100 | $1,200 | $24.00 (2.0% Tangerine) | $18.00 (1.5% Simplii) | $24.00 (Tangerine 2%) |
| Other Retail / Misc | $100 | $1,200 | $6.00 (0.5% Base) | $6.00 (0.5% Base) | $6.00 (0.5% Base) |
| Total Annual Cash Back | $1,200 | $14,400 | $207.00 CAD | $309.00 CAD | $354.00 CAD |
| Net Effective Return | — | — | 1.44% Net Yield | 2.15% Net Yield | 2.46% Net Yield ($0 Fee) |
Notice the power of the combination: carrying both cards boosts annual cash back to $354.00 CAD—a full $147 more than Tangerine alone and $45 more than Simplii alone, with completely zero annual fees.
The Ultimate $0-Fee Duo Strategy: How to Pair Both Cards
Because neither card charges an annual fee, there is zero financial penalty for holding both in your wallet. The synergy between Tangerine and Simplii creates a complete rewards network:
- Simplii Handles Dining (4% Cash Back): Dedicate your Simplii Visa exclusively to restaurants, takeout, pubs, and coffee runs. At 4%, it outperforms virtually every premium card in Canada on dining except the American Express Cobalt ($155.88 fee).
- Tangerine Covers Groceries, Bills & Home Improvement (2% Cash Back): Configure your 3 Tangerine categories to:
- Category 1: Groceries (earning 2% at all supermarkets, including Loblaws and No Frills on Mastercard).
- Category 2: Recurring Bill Payments (earning 2% on telecom, streaming, and hydro bills).
- Category 3: Home Improvement or Gas (earning 2% at Canadian Tire, Home Depot, or gas stations).
- Costco Acceptance Security: Because Costco Canada checkouts only accept Mastercard, the Tangerine card ensures you earn rewards at Costco registers (and at 2% if you order via select online methods or home improvement categories), whereas Simplii Visa is declined at physical registers. Learn more in our CIBC Costco Mastercard review.
How WalletFit Solves Multi-Card Management
Juggling two cards with multiple categories and spending thresholds can lead to rewards leaks if you accidentally swipe the wrong plastic. That is where WalletFit excels:
- Smart Merchant Routing: When you pull out your phone at a restaurant, WalletFit immediately highlights your Simplii card for 4% cash back. When shopping at No Frills or Canadian Tire, WalletFit directs you to Tangerine for 2%.
- Simplii $5,000 Dining Cap Monitor: The engine tracks your year-to-date dining spend on Simplii. As soon as you hit the $5,000 ceiling, WalletFit automatically re-routes your restaurant spending to Tangerine (or an alternative card) so you never settle for 0.5% base rates.
- Annual Fee Breakeven Modeling: WalletFit compares your actual monthly spending against fee-charging heavyweights like the CIBC Dividend Visa Infinite and Canada's best cash back cards, revealing the exact mathematical inflection point where upgrading to a fee card puts more net cash in your pocket.
Frequently Asked Questions
Which card is better: Tangerine Money-Back Mastercard or Simplii Cash Back Visa?
Neither card is strictly better in every scenario; their strengths complement each other. Simplii Financial Cash Back Visa dominates restaurant, bar, and takeout dining with an aggressive 4% cash back rate (up to $5,000 annual spend). The Tangerine Money-Back Mastercard dominates flexibility, offering 2% unlimited cash back across 3 self-selected categories (such as groceries, recurring bills, and home improvement) on the Mastercard network with no spending caps.
How does the cash back payout frequency compare between Tangerine and Simplii?
Tangerine deposits your cash back earnings monthly, either directly into a Tangerine Savings Account (where it earns high interest immediately) or as an automatic statement credit. In contrast, Simplii Financial accumulates your cash back over the entire calendar year and pays it out only once annually on your December billing statement.
Can you use the Tangerine Mastercard and Simplii Visa together?
Yes, pairing both cards creates one of Canada's most effective zero-annual-fee credit card combinations. By routing all dining and takeout to the Simplii Visa for 4% cash back, and selecting Groceries, Recurring Bills, and Drugstore on the Tangerine Mastercard for 2% cash back, you earn elevated returns across four major household budget categories for an effective $0 annual cost.
Are there spending caps on Tangerine's 2% categories?
No. Unlike Simplii Financial (which caps 4% dining at $5,000 per calendar year and 1.5% categories at $15,000), the Tangerine Money-Back Mastercard has no spending cap on its 2% categories. You earn 2% cash back on every dollar spent in your chosen categories with zero monthly or annual ceilings.
Stop Leaving Rewards On The Table
WalletFit automatically tracks spending caps across 50+ Canadian credit cards so you always know the exact card to tap for maximum points and cash back.
Related Canadian Credit Card & Cash Back Guides
- Best no-annual-fee credit card trio in Canada: Pairing Tangerine, Simplii, and Rogers for $600+/yr in net rewards.
- Best credit cards for dining and takeout (2026 Tier List): Complete rankings for restaurants & apps.
- Best credit cards for newcomers to Canada: No credit history required.
- best cash back credit cards in Canada: Complete rankings for top cash earners.
- CIBC Dividend Visa Infinite review: 4% groceries & gas math.
- MBNA Rewards World Elite review: 5x points on groceries & utilities.
- CIBC Costco Mastercard review: Warehouse club companion optimization.
- best grocery credit cards in Canada: Supermarket rewards analysis.
- top Canadian credit cards overall: Canada's top 10 credit cards ranked.