Rewards Card Deep Dive: Cap-Aware Swaps to Maximize Returns
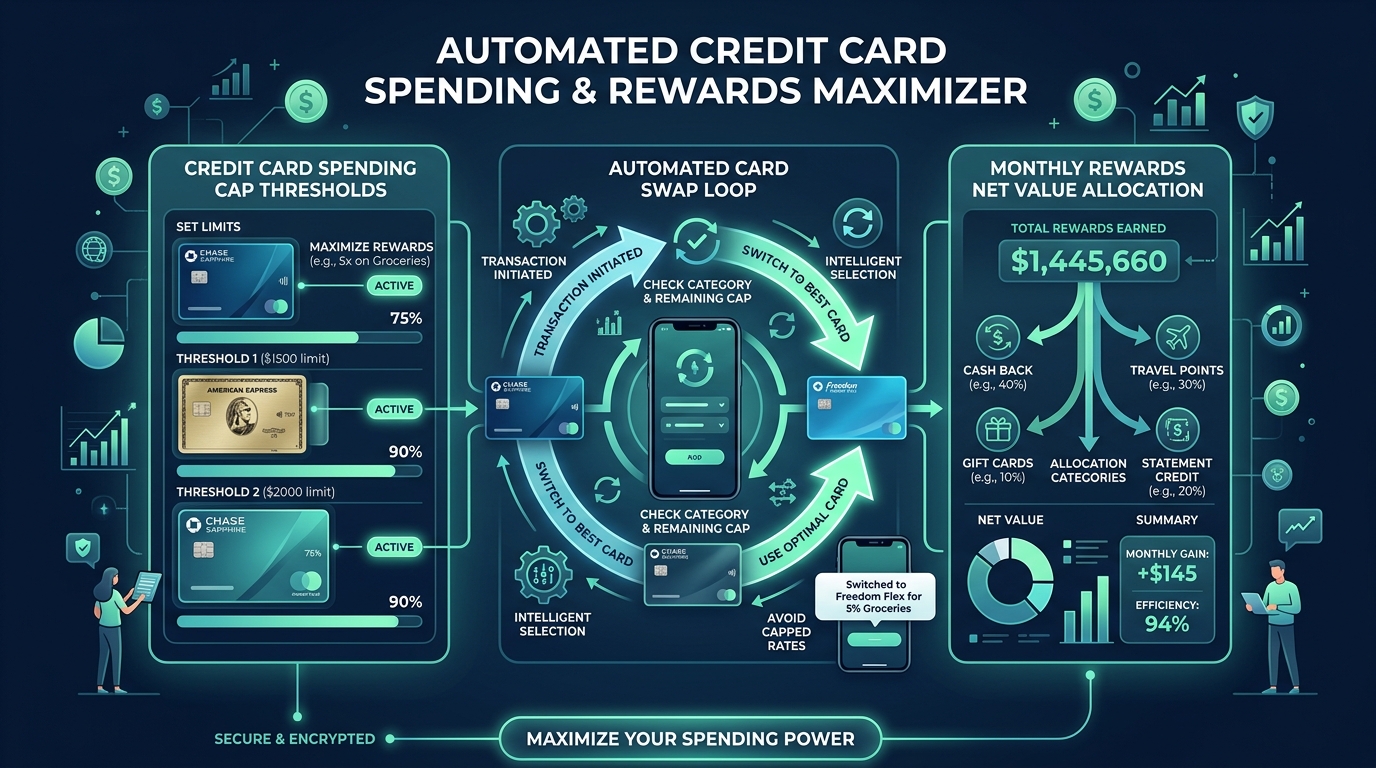
A Rewards Card Deep Dive is a cap-aware swap loop that turns your monthly spend rules into net rewards decisions. It selects the right spend rule, simulates true value, swaps cards when caps change, then re-runs monthly so you stop relying on spreadsheets.
What is a Rewards Card Deep Dive Actually Trying to Solve for Canadians?
A Rewards Card Deep Dive focuses on net rewards outcomes, not raw point totals. It models how redemption choices and purchase categories affect what you actually get, so a “best card” can change when spend caps or merchant rules shift.
The core problem is mismatch: your cards advertise one thing, but your wallet experience depends on utilization of caps, eligible spend, and how points convert to cash back or travel value. In one internal benchmark, users reported satisfaction with core-optimizer outputs at 4.2/5.
For the bigger context on why card rewards value can differ from what you expect, see the Federal Reserve’s look at reward redistribution in the credit card system: Redistribution in the Credit Card System.
Which Swap Rules Should You Use When Categories and Caps Stop Paying?
When your categories fade or caps tighten, the right swap rule depends on how each card earns. Use a cap-aware swap rule when spending limits drive the result, a promo-aware rule when time-bound offers matter, and a flat-rate default when category matching becomes unreliable.
| Card earning model (what drives points) | When your cap status should trigger a swap | Input signals to check before switching | What the swap rule should do next |
|---|---|---|---|
| Flat-rate cash back (one rate everywhere) |
Caps are reached, but category matching does not change value | Remaining cap, your overall spend mix | Stick to the highest net value card until a cap forces the next switch |
| Category multipliers (bonus by merchant category) |
Categories stop paying because you fall outside eligibility ranges | Category match, excluded MCC-like patterns, how often you hit those categories | Route by category first, then switch to a non-degrading card when eligibility drops |
| Capped category or offer (bonuses with ceilings) |
The cap approaches or resets in a way that changes net value | Cap remaining, reset timing, whether “extra” earn is still active | Run the Cap-Aware Swap Loop, swapping as soon as the simulated net value flips |
| Portal or partner earn (bonus via entry points) |
Your normal checkout path bypasses partner terms | Portal eligibility, whether you are using the required channel | Force a rule switch only when the correct path is available, otherwise keep routing by base earn |
| Transfer / points ecosystem (value depends on redemption) |
Redemption value becomes uneven across your planned timeline | Intended redemption option, point valuation choices per program, month-by-month plan | Simulate net value using your redemption assumptions, then swap only when ecosystem value changes |
The practical choice is to let one rule own each “failure mode.” If your category multipliers go quiet because your purchases drift, category multipliers should stop being the top signal and cap-aware routing should take over. If a card’s upside is tied to an offer ceiling, you should treat cap remaining as the primary clock, not gut feel.
If you are running Wallet Fit’s Cap-Aware Swap Loop, the clean workflow is: select the spend rule, simulate net value using your own point valuations, swap cards when a cap changes the winner, then re-run monthly as your transaction mix updates. This avoids the common mistake of continuing the “best card” plan even after the earning math quietly stopped matching your life.
When you cannot confidently match category eligibility or partner terms, fall back to the flat-rate default rule. You get fewer dramatic wins, but you also stop paying for uncertainty with missed multipliers. Over time, that restraint usually beats heroic manual spreadsheeting.
How Do Rewards Card Earnings, Redemptions, and “Value Decay” Fit Together?
A rewards card only pays what survives the full path from purchase to redemption, and the “survival” step is where earnings turn into usable value. Earnings are the easy part, redemptions are where mechanics differ, and value decay is what happens when fees, interest, friction, or partial eligibility quietly eat the upside. Model the whole lifecycle, not just point totals.
“Points earned” and “value kept” can diverge fast in real wallets. One common trap is assuming every card redeems the same way, then realizing statement credits, transfers, and cashback have different rules and breakpoints. Another trap is letting redemption friction push you into a less favorable option, which is basically negative opportunity cost.
Per the Federal Reserve’s Who Pays For Your Rewards? Redistribution in the Credit Card System, rewards can show a negative average net reward once interest charges and fees are included (Federal Reserve Study).
Why Value Points Differently Depending on the Rewards Ecosystem?
Valuing points changes because each rewards ecosystem converts balances into money differently, and those conversion rules vary by redemption channel. A cents-per-point number breaks when statement credits, transfers, and cashback behave unlike each other. You need an ecosystem-aware net-value estimate, not a single constant.
When someone says “I got 10,000 points,” the real question is what is the net outcome after redemption mechanics? One card might turn points into instant statement credit with no extra steps, while another requires a transfer, timing, or a portal path. And those choices can shift the outcome even when the earnings rate is identical for the same purchase category.
For a practical reminder of how outcome rules matter, see how the Savings Project frames rewards redemption as part of the household value decision: Savings Project Case Study.
When Do Caps, Merchant Categories, and “Good Enough” Breakpoints Change the Answer?
Caps and merchant categories change the answer when the marginal value of switching cards becomes bigger than your effort and constraints. “Good enough” breakpoints are the moments where chasing the perfect card produces smaller net gains than the time, eligibility limits, and redemption friction you introduce.
In practice, this often shows up after a month’s cap utilization, when merchant categories drift from where the same card stays best. When the remaining eligible spend is thin, a “close enough” card prevents churn that yields small incremental improvements.
One case study found that simplifying redemption choices by framing redemptions to savings as the default and reducing clicks doubled the number of cash-back rewards cardholders who completed a savings-oriented redemption (a 2x increase, per the Savings Project Case Study). A Rewards Card Deep Dive becomes a loop only when these breakpoints reliably trigger reassessment, not obsession.
What Should You Do First to Maximize Returns Without Building a Spreadsheet?
Start with a small monthly rules sheet, not a massive spreadsheet. Map your spend categories, note promo windows, and list each card’s cap constraints. Then simulate net value for each eligible purchase type, and only swap when the cap is actually limiting your rewards.
Identify annual/monthly caps, redemption limits, and any merchant eligibility quirks across your active wallet.
Isolate your highest spending streams: groceries, transit, dining, travel, recurring bills, and anything with an active promo window.
Factor in your realistic redemption plan, especially where statement credits (fixed 1¢) and travel transfers (1.5¢–2.2¢) diverge.
Select your primary spend rule, simulate net value against current spend, and choose the card that wins under remaining cap headroom.
Ensure each month begins with updated cap tracking and fresh allocations rather than stale assumptions.
As a sanity check, the Federal Reserve’s research is a reminder that gross rewards alone can mislead, and net outcomes matter more (Federal Reserve Paper). For most people, this 5-step loop stops spreadsheet churn and catches obvious mis-swaps.
What Do Experts Say Breaks Multi-Card Optimization the Most?
Multi-card optimization breaks most often when people optimize only one layer—such as gross points earned—and ignore the layers that turn rewards into net value. They often overlook friction, eligibility gaps, and the true net cost of holding cards. Value also leaks when cardholders chase points without mapping the redemption path, timing, or whether rewards will actually be usable when the annual fee comes due.
“Credit card rewards depend on how you redeem, not just what you earn.”
— Kiplinger, How to Make the Most Of Your Credit Card Rewards in 2025 (Source)“Rewards value depends on context and the full card lifecycle, not a single headline rate.”
— Political Economy Research Council (PERC), Rewards Value Framing Report (Source)In practice, this looks like a card that is “best” on paper being blocked by a cap, or a category rule being narrower than your expectation, leaving you with points that are harder to use. The fix is disciplined loop inputs, then a one-pass swap simulation before you commit to the month’s routing.
Is Multi-Card Optimization Worth It, or Just Over-Engineering?
Multi-card optimization is not worth it when the effort and complexity push you into net-negative outcomes. The time cost, plus uncertainty around caps, redemptions, and card terms, can erase expected gains. If carrying balances or paying unrecouped fees becomes part of the picture, an “optimized” plan can significantly underperform a simple no-fee flat card.
A fair steelman is that rewards cards become net-negative when interest and fees eat the rewards. The Federal Reserve paper discusses how higher interest charges can reduce or reverse the advantage of reward cards, especially when balances carry (Federal Reserve Research). That reality is why optimization should start with constraints and net value, not vanity multipliers.
That said, the work can be small if you treat it like a monthly routine. In one internal benchmark, the core-optimizer workflow completion rate was 87%, which proves the loop is feasible without spreadsheet-heavy tracking. If your month has stable recurring spend and you track caps at a rules level, multi-card optimization stops being complex engineering and becomes a repeatable allocation step.
Frequently Asked Questions
Do rewards cards in Canada ever end up costing you money even if you earn points?
Yes. Points can still lose to interest, fees, or friction if you carry a balance, miss promo conditions, or face redemption limits. The Federal Reserve has discussed how higher interest charges can reduce or reverse the advantage of reward cards (Federal Reserve paper).
What’s the fastest way to decide which card to use for groceries, dining, and gas without tracking apps?
Use a Cap-Aware Swap Loop: choose a single spend rule, simulate net value for that spend type, then only swap when your cap is actually limiting. Keep merchant categories and your remaining eligible spend visible for the week, not the whole year, then update monthly.
Should you redeem for cashback/statement credit or save points for transfers?
Pick based on how each redemption path affects “value kept” after taxes, fees, and any transfer requirements. Statement credits are usually simpler, while transfers can pay off when your points match a travel program you can actually book. Kiplinger’s guidance focuses on aligning redemption method with your plan (Kiplinger).
How do annual fees affect whether a rewards card is actually worth it?
Fees turn your optimization from “maximize earning” into “maximize net value.” If your eligible spend is small or your cap is frequently exhausted, the same earn rate can look mediocre after fees. A cash-back comparison mindset helps, but you still need to model your redemption friction, not just point totals.
Why do multipliers and promos sometimes feel great on paper but worse in real value?
Multipliers often ignore caps, eligibility constraints, and redemption mechanics. When a promo overlaps the portion of spend you would have assigned to a different card, the marginal gain shrinks. Then value decay from redemption friction or missed conditions can erase the headline boost quickly.
Automate Your Cap-Aware Swap Loop with Wallet Fit
Let our algorithmic engine track your category caps in real time, forecast multiplier resets, and automatically assign the highest net-return card to every purchase.
Start Cap-Aware Optimization